
By Palak Devpura
You own 60 percent of the company. Your investor owns 20 percent. So you control the company, right?
Not always.
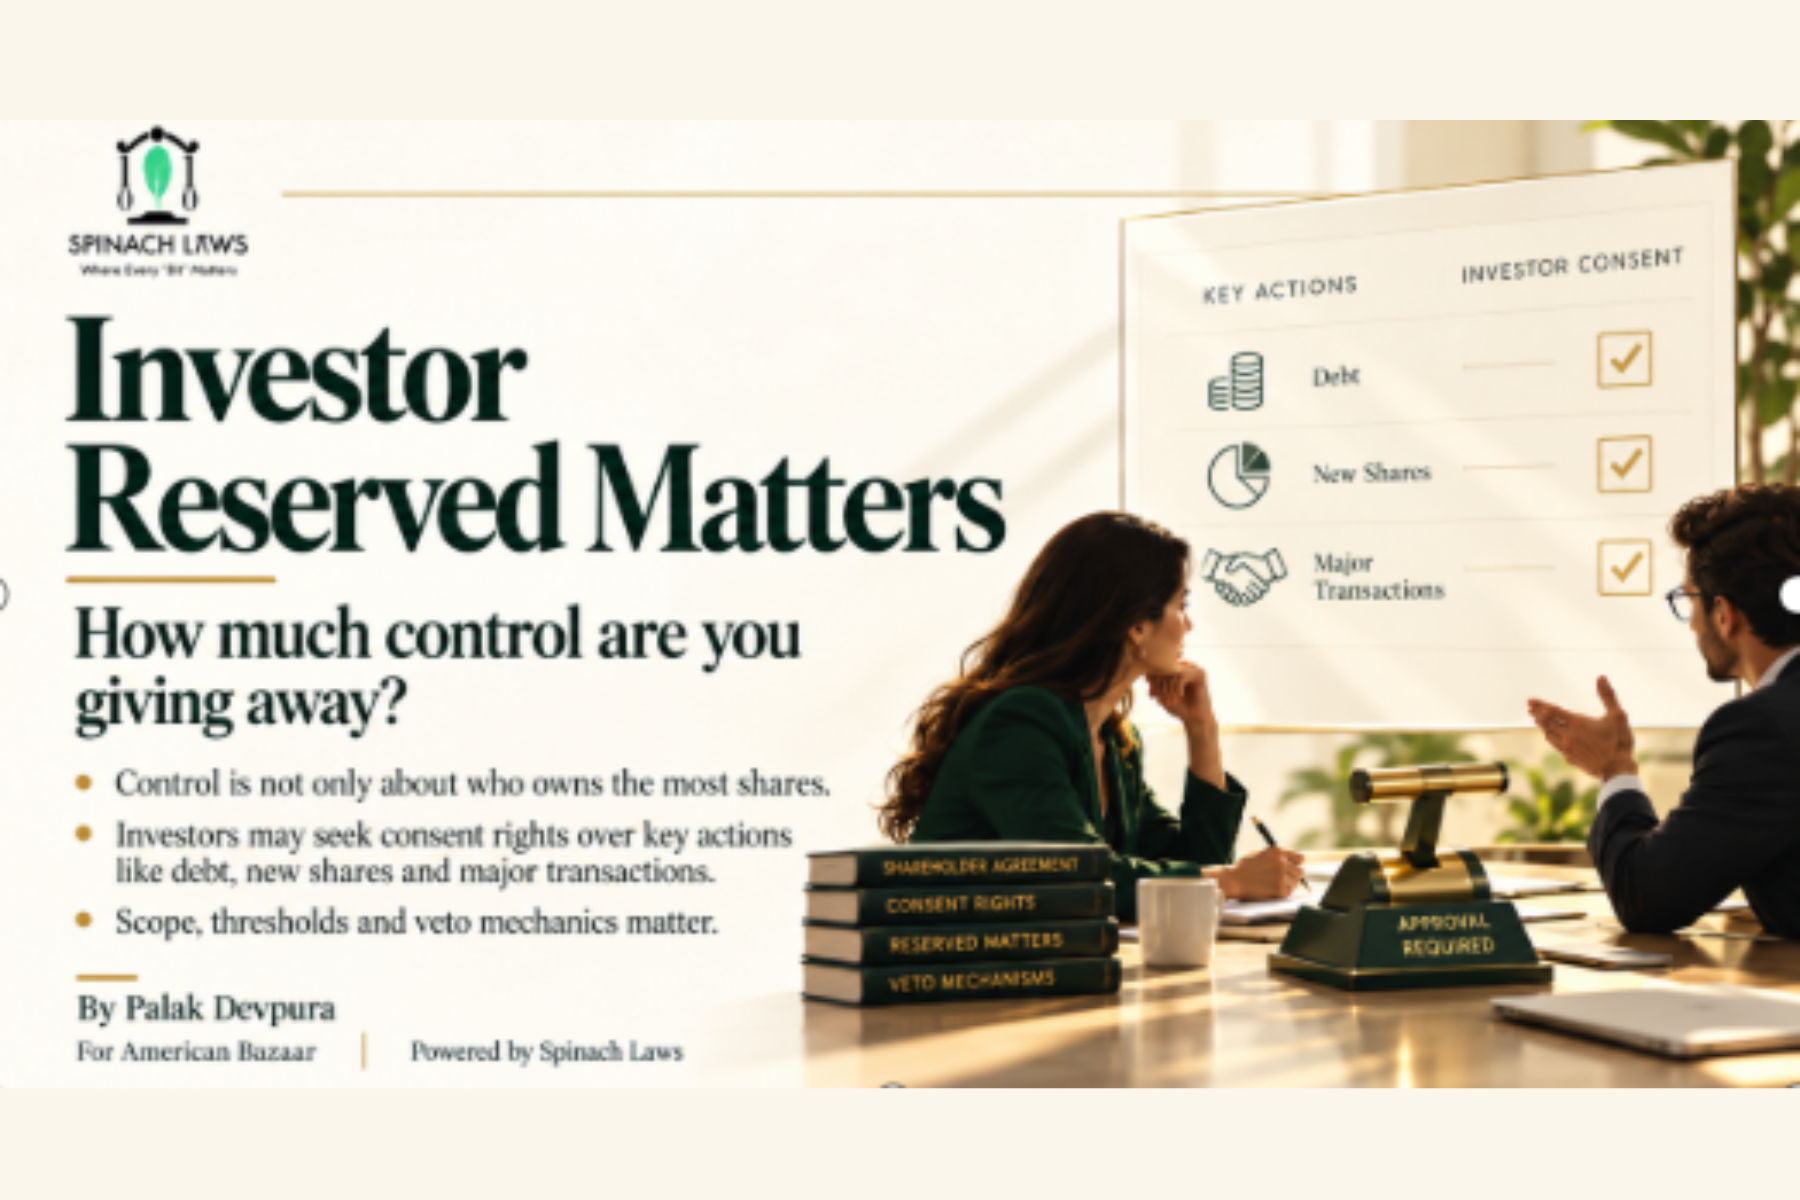
A fundraising round changes more than the cap table. Investors often negotiate reserved matters, sometimes called affirmative vote matters, that require their consent before the company can take specified actions. The founder may still hold the largest economic stake but no longer have unilateral freedom over certain strategic decisions.
What kinds of decisions are we talking about? Typical lists can include issuing new shares, taking significant debt, changing the nature of the business, acquiring or selling a business, amending charter documents, approving certain budgets, entering related party transactions, appointing or removing key executives, creating security over assets, declaring dividends or undertaking an IPO.
Read: What happens after a startup receives a term sheet? (October 13, 2026)
From the investor’s perspective, this makes sense. They may own a minority stake and cannot rely on ordinary voting power to stop a decision that could fundamentally alter the value of their investment. Reserved matters are therefore a governance protection.
From the founder’s perspective, the question is scope. If every meaningful operating decision requires investor approval, the company can become difficult to run. A ₹5 lakh vendor contract should not necessarily be treated like a ₹5 crore acquisition. Thresholds, materiality and decision categories matter.
Founders should also pay attention to who actually holds the veto. Is consent needed from one named investor? A majority of a defined major investor class? An investor director? What happens if the investor’s stake falls below a negotiated threshold? Do the rights terminate after an IPO or transfer?
Read: What is liquidation preference in a term sheet? (October 15, 2026)
The most practical exercise is to take the reserved matters schedule and imagine a normal year in the company. Hiring a senior leader. Raising debt. Launching a new business line. Issuing ESOPs. Acquiring a smaller competitor. Which of these would require someone else’s signature?
This does not mean founders should fear governance rights. Good investors can bring discipline and prevent impulsive decisions. But governance should protect the investment without turning the founders into operators who need permission for ordinary business.
Before you celebrate retaining 60 percent after a round, read the rights attached to the other 40 percent.
Ownership tells you who holds the shares. Reserved matters tell you who may hold the brakes.
(Palak Devpura is co-founder of Spinach Laws, a startup-focused legal services firm advising founders on incorporation, brand protection and cross-border transactions. This column is part of the ongoing Spinach Laws × The American Bazaar series on law for founders.)