
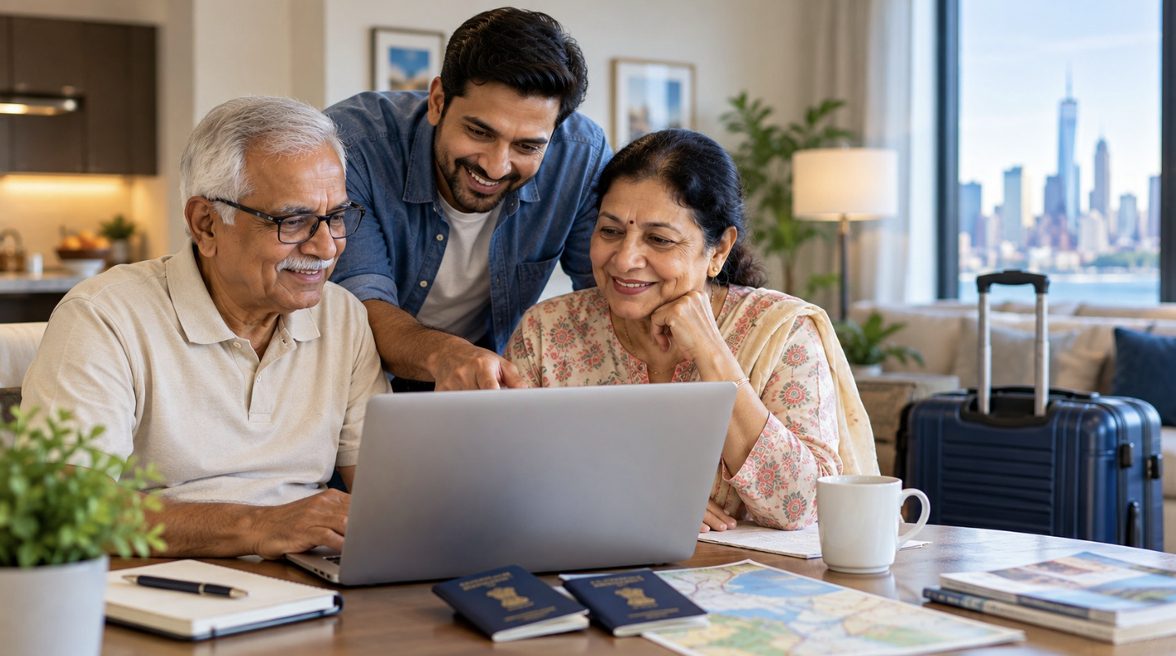
Many Non-Resident Indians (NRIs) arrange visitor medical insurance for their parents before they travel to the United States. However, some families realize only after arrival that their parents are uninsured or that their planned stay will be longer than expected.
This raises an important question: Can you buy visitor health insurance after arriving in the U.S.?
Yes, many visitor medical insurance plans allow eligible travelers to purchase coverage after arrival. Availability depends on the insurance plan, the traveler’s eligibility, and the policy’s terms. Importantly, buying a policy after arrival does not mean that medical expenses incurred before its effective date will be covered.
For NRIs whose parents or relatives are already in the United States, understanding purchase eligibility, coverage start dates, pre-existing condition provisions, and waiting periods is essential before choosing a plan.
Can visitors buy visitor health insurance after arriving in the US?
Yes, many visitor health insurance plans allow eligible travelers to purchase coverage after arriving in the United States.
This option may be relevant when:
- Parents arrive from India without purchasing insurance before departure.
- The visitor’s stay in the United States has been unexpectedly extended.
- Family members realize that a visiting parent or relative is uninsured.
- An existing policy is approaching expiration, and the family is exploring additional coverage.
However, not every plan permits purchase after arrival. Some plans have specific eligibility requirements, purchase restrictions, or conditions that affect coverage.
Before buying, confirm that the selected plan accepts applicants who are already in the United States and check its effective-date rules.
Important: A new policy generally does not cover an illness, injury, or medical expense that occurred before the policy’s effective date. Coverage is subject to the specific policy’s terms and exclusions.
When does the coverage start?
An effective date is one of the most important things to check when purchasing visitor health insurance after arrival.
Policies do not necessarily begin simply because the application has been submitted, or payment has been completed. The policy will have a stated effective date, and coverage generally applies to eligible events occurring during the covered period.
For example, imagine a parent arrives in the U.S. on October 1 without insurance and purchases visitor health insurance on October 5. If the policy becomes effective on October 6, an illness or injury that occurred before October 6 would generally not become covered simply because the policy was purchased afterward.
Therefore, NRIs should carefully check the effective date before completing the purchase.
Can a new policy cover an illness that has already started?
Generally, visitor health insurance is intended to cover eligible new and unexpected medical conditions that occur after coverage begins, subject to the policy terms.
It is not designed to provide retroactive coverage.
For example, suppose a visitor develops severe abdominal pain on Monday, receives medical treatment on Tuesday, and purchases visitor health insurance on Wednesday.
The Wednesday purchase would generally not make Monday’s or Tuesday’s medical expenses eligible under the new policy.
This is one of the most important points for families to understand. Waiting until a medical problem occurs before purchasing coverage can leave the traveler responsible for expenses related to that existing medical event.
What about pre-existing medical conditions?
Pre-existing conditions require additional attention, especially when parents or older relatives are visiting from India.
Many visitor health insurance plans exclude pre-existing conditions or provide only limited coverage under specific circumstances.
Some plans may include benefits for an acute onset of a pre-existing condition, subject to the plan’s definition and eligibility requirements.
For example, a traveler may have a history of diabetes, hypertension, or heart disease. If the traveler experiences a sudden medical event related to an existing condition, coverage will depend on whether the event satisfies the policy’s definition of acute onset.
Travelers should not assume that simply having a pre-existing condition means all related medical treatment will be covered.
The policy wording, age requirements, benefit limits, exclusions, and other conditions must be reviewed carefully.
What does “acute onset” mean?
The term acute onset of a pre-existing condition can be confusing.
Generally, it refers to a sudden and unexpected recurrence or worsening of an existing medical condition that meets the insurance policy’s specific definition.
It should not interpret as comprehensive coverage for ongoing treatment.
For example, routine medical appointments, prescription refills, planned treatment, or regular management of diabetes or hypertension should not automatically be assumed to qualify.
Each insurance plan defines acute onset differently, and some plans impose additional age or treatment requirements.
This is particularly important when buying coverage after arrival as a medical condition that began before the policy’s effective date may not qualify as a newly covered event.
Does age affect visitor health insurance?
Yes. Age can affect both the availability and cost of visitor health insurance.
Older travelers may have:
- Higher premiums
- Different policy maximum options
- Age-specific benefit limits
- Different eligibility requirements
- Additional restrictions involving pre-existing conditions.
This is particularly relevant for parents and grandparents visiting the U.S. from India.
For example, a 45-year-old visitor and a 70-year-old visitor may be traveling for the same number of days, but their visitor health insurance premiums and available plan options may be different.
Families should therefore enter the visitor’s actual age when obtaining a quote and review the coverage available for that particular age group.
What if the visitor is already in the U.S. and healthy?
This is generally a straightforward situation to evaluate.
If a visitor is already in the United States, has not experienced a medical problem, and is eligible for a plan that permits purchase after arrival, obtaining coverage can help protect against eligible future medical expenses during the remaining trip.
The earlier the coverage is arranged, the smaller the period during which the visitor remains uninsured.
However, the policy’s effective date and other terms still apply.
What if the visitor is already sick?
This situation requires considerably more caution.
If a visitor is already experiencing symptoms or has already received medical treatment before purchasing a policy, the family should not assume that the new insurance will cover the condition.
For example, if a visitor develops chest pain before purchasing coverage and then buys a policy afterward, subsequent treatment for that same medical episode may be subject to exclusions or limitations.
The insurance company may evaluate when the symptoms began, when treatment was first sought, and whether the condition existed before the policy’s effective date.
The exact determination depends on the applicable policy wordings.
What should NRIs check before buying insurance after arrival?
Before purchasing a plan for a parent or relative already in the United States, review the following checklist.
| What to check | Why it matters |
| Purchase eligibility | Confirms that the plan permits eligible travelers already in the U.S. to enroll. |
| Effective date | Establish when the coverage period begins. |
| Waiting periods | Identifies any delays or restrictions affecting specified benefits. |
| Pre-existing conditions | Explains which conditions are excluded or may qualify for limited benefits. |
| Age restrictions | Determines eligibility and available benefits for the traveler’s age. |
| Deductible | Shows the amount the insured must pay under the policy before applicable benefits are paid. |
| Policy maximum | Identifies the maximum payable amount, subject to the policy’s terms and any separate limits. |
| PPO network | Helps families understand provider access and possible billing arrangements. |
| Claims requirements | Explains notification procedures, documentation, and applicable deadlines. |
| Coverage duration | Helps ensure the requested coverage period matches the remaining trip. |
A lower premium does not necessarily mean better protection. Compare the benefits, exclusions, and out-of-pocket responsibilities before selecting a plan.
What if the visitor extends their stay in the United States?
Parents sometimes plan to stay for two or three months but later decide to remain longer with their children.
If the visitor already has insurance, check the existing policy’s extension or renewal provisions before coverage expires. Options depend on the plan, and the applicable conditions.
If an extension is not available, a family may investigate whether another eligible plan can be purchased. However, a new policy may have different eligibility rules, effective dates, exclusions, and limitations.
Avoid assuming that a new policy will cover medical conditions that developed during the previous coverage period. Review the applicable terms carefully to understand whether a change in coverage could affect protection for an existing condition.
Is it better to buy visitor insurance before or after arrival?
Buying visitor medical insurance before departure is generally preferable because it can reduce the period during which a traveler is uninsured. It also gives families more time to compare plans and understand their benefits before the trip begins.
Before departure, families can review:
- Premiums and policy maximums.
- Deductible and cost-sharing requirements.
- Coverage for eligible illnesses and injuries.
- Pre-existing condition provisions.
- Age eligibility and benefit restrictions.
- PPO networks and billing arrangements.
- Coverage dates and extension options.
If a parent or relative has already arrived without insurance, however, eligible post-arrival options may still be available. The family should investigate them promptly while recognizing that a newly purchased policy generally will not cover prior medical expenses.
You can also explore visitor insurance options for travel to the USA from India to learn more about coverage considerations for international travelers.
The bottom line
Visitors may be able to purchase visitor health insurance after arriving in the United States, depending on the specific plan and eligibility requirements.
But there is an important limitation: A policy purchased after arrival does not provide retroactive coverage for an illness, injury, or medical expenses that began before the policy’s effective date.
For this reason, NRIs should not wait until a parent becomes sick to start thinking about insurance.
Ideally, visitor health insurance should be arranged before the traveler leaves India. If a parent or relative has already arrived without coverage, the family should review eligible options as soon as possible and carefully check the effective date, exclusions, waiting periods, age restrictions, deductible, policy maximum, and pre-existing-condition provisions.
Visitor health insurance can provide valuable financial protection against eligible unexpected medical expenses during a U.S. visit. The key is understanding what the policy covers and when that coverage actually begins.
Disclaimer: Visitor health insurance benefits, premiums, eligibility requirements, effective dates, exclusions, waiting periods, age restrictions, deductibles, and pre-existing-condition provisions vary by plan and provider. Travelers should review policy documents carefully before purchasing coverage.