
By Palak Devpura
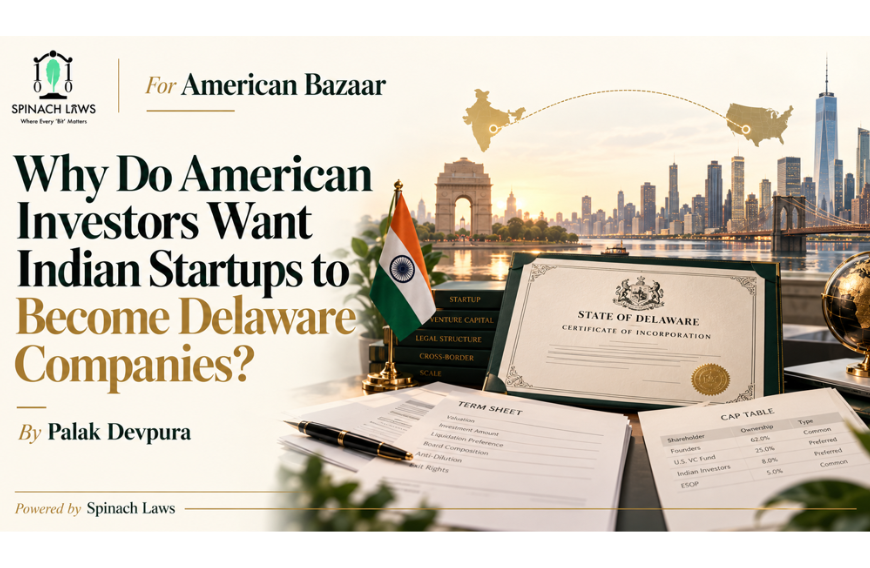
An Indian founder has built a promising software company. Customers are signing up, revenue is growing and a U.S. venture capital fund is ready to invest. Then comes an unexpected request: “Can you set up a Delaware company first?”
The founder wonders why a business built in Bengaluru needs an American corporate address to raise money.
The answer is not that Delaware magically improves a product. It is that investors prefer a legal structure they already understand.
Delaware has a well-developed corporate law system and a specialist Court of Chancery that handles many business disputes. American venture funds and their lawyers are familiar with its rules, shareholder protections and financing documents. That familiarity can make complex investment negotiations more predictable.
READ: Indian AI startups eye US expansion but face tough fight to win American customers (October 28, 2026)
The Delaware C corporation is also well suited to venture financing. It can issue different classes of shares, including preferred shares with negotiated investor rights. Employee stock options, board arrangements and future funding rounds can be organised through structures familiar to U.S. investors.
For an Indian startup, however, the decision is rarely as simple as filing incorporation paperwork. A U.S. parent company might hold shares in an Indian operating subsidiary. Sometimes founders consider transferring ownership or restructuring an existing group, a process often called a “flip”.
These arrangements require careful examination of Indian foreign exchange rules, taxes, share valuations, intellectual property ownership and both countries’ reporting obligations.
And there are practical costs. A Delaware entity may have ongoing franchise taxes, registered agent fees, accounting requirements and additional legal paperwork. Incorporating there does not automatically eliminate taxes in other places where the business operates.
READ: Indian AI startups weigh costs of moving to US (October 28, 2026)
Nor does every American investor insist on this structure. The right answer depends on the investment fund, the startup’s business model, where its customers and employees are located, and its long-term plans.
Before restructuring, founders should ask a more useful question than “How quickly can we incorporate in Delaware?” They should ask, “What problem does this structure solve for our business, and what new obligations will it create?”
An investor-friendly company is valuable. But a structure that pleases investors while creating avoidable complexity for the business is not automatically a better one.
(Palak Devpura is co-founder of Spinach Laws, a startup-focused legal services firm advising founders on incorporation, brand protection and cross-border transactions. This column is part of the ongoing Spinach Laws × The American Bazaar series on law for founders.)