

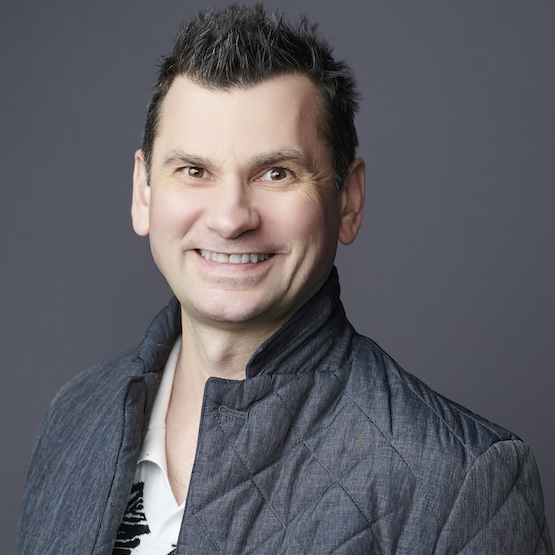
Rokas Beresniovas has been a fixture in these pages for nearly a decade, writing on business, finance, and sustainability. In April, he published his first book, Green as a Lever, a capital-markets playbook for real estate developers. Now word has reached us that he’s at it again — a second book, this time for the tens of millions of Americans who live in condos, co-ops, and HOA communities. With over 20 years in finance and his current role as Head of Partnerships at the Montgomery County Green Bank, he agreed to tell us what he’s been working on.
We caught up with him to ask about the book that’s coming.
So we hear you’re launching another book. What is it, and why this one now?
It’s called Green as a Lifeline: The Condo, Co-op, and HOA Playbook for Lower Fees, Smarter Upgrades, and Buildings That Last. It’s coming out October 27 in paperback and e-book, with an audiobook to follow. Lever was written for the people who build real estate. But most Americans don’t develop property — they live in it. And tens of millions live in community associations where their individual homes are tied to shared infrastructure, shared costs, and collective decisions. There are roughly 373,000 of these community associations in the country, home to more than 78 million Americans and representing about one-third of the U.S. housing stock. I spent five years at the Green Bank running into this same asset class over and over, and I couldn’t find a book that connected governance, reserves, financing, and building upgrades in a practical way. So I wrote one.
The title is Green as a Lifeline. That’s a big step up in urgency from Lever.
Deliberately. A lever is a tool you choose to use. A lifeline is something you reach for when you’re already in trouble — and a lot of these communities are already in trouble, they just can’t see it yet, because the warning signs are buried in a monthly fee most owners treat as a bill instead of a diagnosis. This book is warmer and more human than the first one, because the stakes are more human. These aren’t spreadsheets. They’re people’s homes, their retirements, their life savings.
You argue these buildings don’t really have a “green” problem. What do you mean?
Same move as the first book, different subject. Everyone assumes the barrier to a better building is awareness, or willpower, or the cost of solar panels. It almost never is. The barrier is that a group of volunteers — neighbors, retirees, people with day jobs — has to agree to spend serious money on infrastructure most of them don’t understand, under bylaws written decades ago by attorneys who never imagined today’s energy and insurance pressures. Over five years at the Green Bank, I tracked these projects from first phone call to signed contract. Based on my own engagements — not a formal study — the average was about three years. For a decision a developer would make in three months. Same building, same economics. The technology isn’t the hard part. The decision is the hard part. So no — it’s not a green problem. It’s a governance problem, and underneath that, a capital problem.
Walk us through how a healthy building quietly gets into trouble.
It runs on the condo fee, and the fee is a black box to almost everyone who pays it. People know the number, they know it goes up, they know they don’t like it — but they don’t know what’s inside it or what it should be. Underneath the fee is the reserve fund, the savings account meant to cover the big-ticket replacements: the roof, the boiler, the garage. In theory you set money aside every year so the cash is there when the bill comes. In practice, boards underfund it — because raising fees is a career-ending speech to deliver at an annual meeting. A board member who raises fees today for a boiler that fails in 2032 pays all the political cost and sees none of the benefit. So the increase gets softened, the timeline gets stretched, and the can gets kicked. Year after year. Until the roof fails eight years early, the reserves are half of what they should be, and everyone gets hit with a special assessment nobody budgeted for. In a condo, every building-level failure is a personal financial event for every owner. You can’t opt out.
When people hear “aging buildings,” they think of Surfside. Is that the extreme version of this?
It’s the catastrophic version. Champlain Towers South collapsed in 2021 and killed 98 people. NIST’s 2026 technical findings traced the collapse largely to deficiencies in the building’s original design and construction, with added loads and long-term corrosion further narrowing already-thin safety margins. Surfside forced the whole country to confront how serious aging-building risk can become. The Foundation for Community Association Research now identifies aging infrastructure as one of the most significant challenges these communities face. Most buildings won’t collapse — but a lot of them will quietly see major building components reach the end of their useful lives at exactly the moment reserves, insurance, and lending have all tightened around them. That’s the pattern behind almost every condo-distress story you read: the insurance pullbacks, the emergency assessments, the buildings that can’t close mortgages anymore.
So what will the book propose?
A reframe, and then the tools to act on it. The reframe is this: stop pitching the board on “spending money to go green.” Nobody votes for that. Pitch it as reducing operating costs and protecting reserves — which is what these upgrades actually do. If a high-efficiency system cuts the building’s energy bill by 20 or 30 percent, that’s cash you can redirect into the reserve gap that’s driving your fees up in the first place. Then you finance the upgrade with patient, affordable capital instead of a special assessment nobody can afford — green bank loans, C-PACE where it’s available, utility incentives that can actually be incorporated into the financing. When you do that, the boiler replacement stops being a crisis and becomes a decision. That’s the whole playbook.
You mentioned C-PACE. It can work for some co-ops but is often harder — or unavailable — for condos. Why does the ownership structure matter so much?
Because it determines everything downstream — what you own, who can borrow, how capital flows in. A co-op is generally a single corporation that owns the whole building, with residents holding shares. That single-entity structure can make certain forms of building-level financing much easier to arrange. A condo fragments ownership across individual units, often with separate tax parcels and mortgages, which can make tools like C-PACE difficult or unavailable depending on the state and the program. It sounds like a technicality. It’s actually the difference between which tools a community can reach for when the bill comes due — and the book spends real time on these distinctions, because every solution later depends on them.
Who is this book for?
The whole ecosystem, because none of these players can fix this alone. Condo and co-op owners who want to understand the check they write every month. Boards, and the property managers and management companies who carry the weight of these decisions. Lenders — conventional banks, CDFIs, and green banks — who sense that underwriting a 40-year-old condo isn’t like underwriting a commercial building and want a better mental model. The engineers, contractors, and energy advisors who do the work. And jurisdictions that have passed, or are weighing, building energy performance laws and are realizing that mandates need to be paired with financing and technical support so they don’t add to the financial stress these buildings already carry. There’s an appendix at the back — sample board resolutions, owner communication templates, reserve study and lender RFP checklists, contractor and energy-advisor rubrics — so it’s not just an argument. It’s a starter kit you can bring to your next board meeting.
This connects to your own life, not just your job.
It does. I’m a condo owner myself, and I sit on my community’s energy committee, so I’ve watched these dynamics from inside the room, not just across a lending table. And the longer view comes from further back — I grew up in Lithuania under Soviet rule, and I saw what happens when rigid systems fail to adapt to changing realities. That’s the lens I bring to these buildings. The structures we inherited weren’t built for the moment they’re now facing. They can adapt — but only if the people inside them can see the problem clearly and act before the bill arrives.
Last question — when can people get it?
It’s coming out October 27 in paperback and e-book, with an audiobook to follow. And if you’ve ever sat in a board meeting watching a decision die for the third year in a row, or opened a special-assessment letter wondering how it got this bad — this is the book I wrote for you.
Green as a Lifeline: The Condo, Co-op, and HOA Playbook for Lower Fees, Smarter Upgrades, and Buildings That Last will be available October 27 in paperback and e-book through Amazon, Barnes & Noble, and other major booksellers, with an audiobook to follow.