
For decades, the American financial markets have enjoyed a unique position in the global economy. Whenever uncertainty spread across the world, investors generally turned toward the United States. The dollar, U.S. Treasury securities and American equities represented stability, liquidity and confidence. Wall Street was not merely a marketplace; it was the financial destination of last resort.
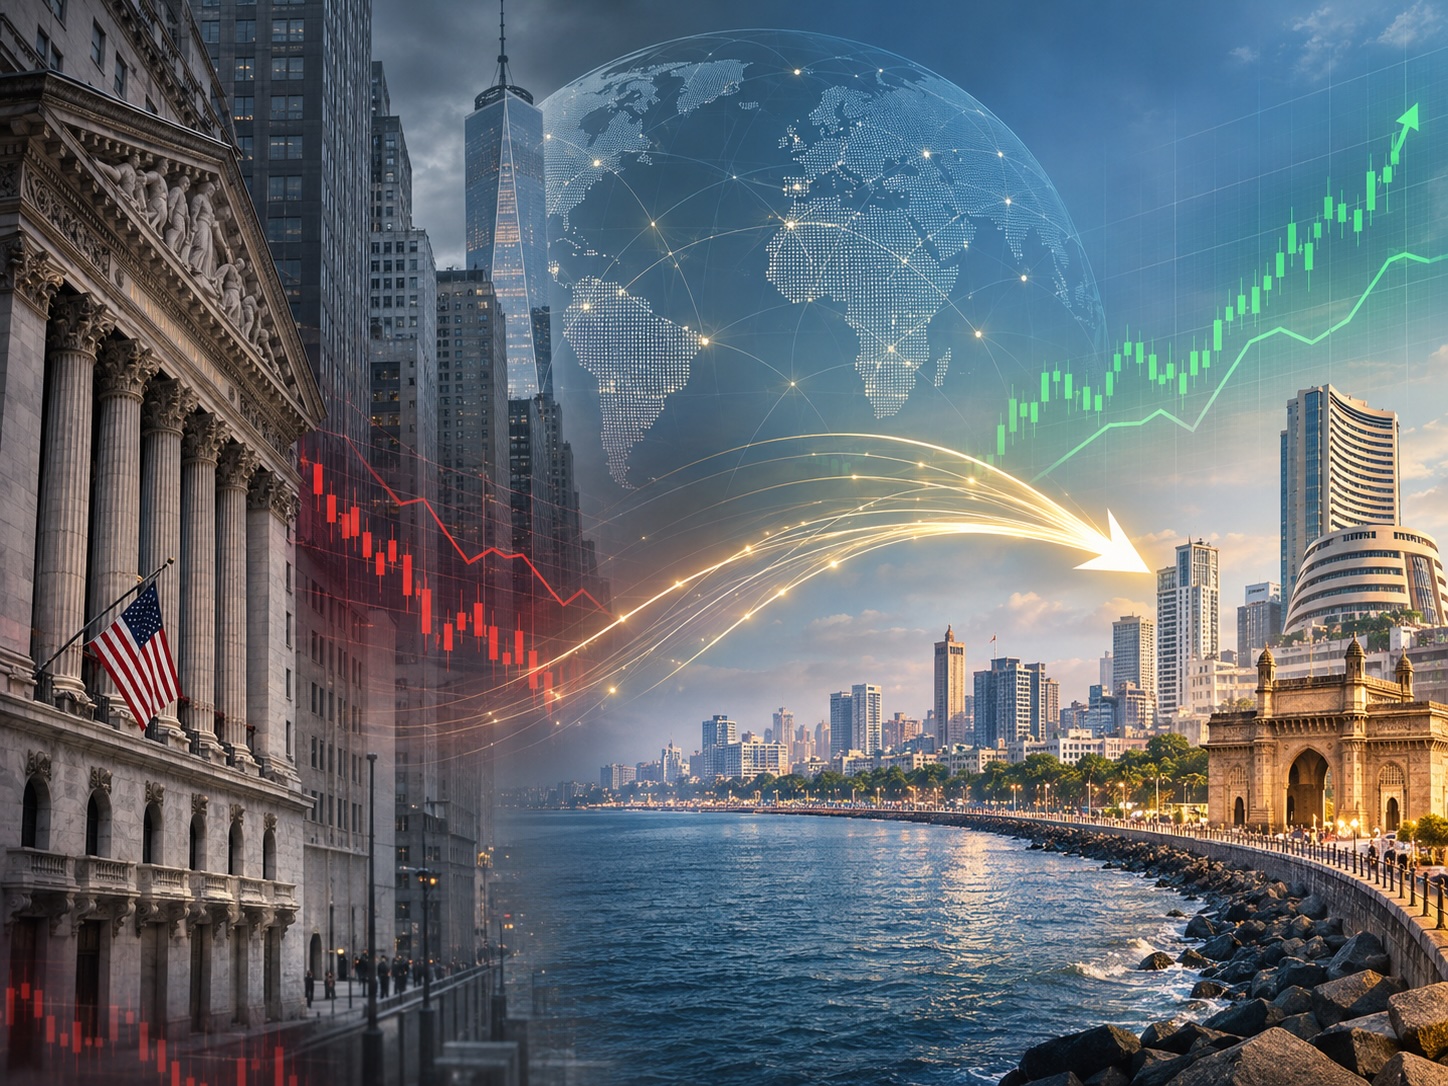
 But something unusual is happening in November 2026. Even as American stocks come under significant pressure, India’s stock market is witnessing a remarkable rally, supported by a resurgence of foreign institutional investment. The contrast raises a question that goes beyond daily market movements: Are global investors beginning to reconsider where they want to put their money?
This may be more than a temporary geographic rotation. It could represent an early indication of changing preferences in global capital allocation.
Wall Street’s trillion-dollar problem
The recent American market decline has been particularly painful for technology investors. The Nasdaq, S&P 500 and Dow Jones have all come under pressure, with semiconductor and artificial intelligence-related companies experiencing significant selling.
The immediate concern is the extraordinary amount of capital invested in the artificial intelligence ecosystem. Over the past several years, companies associated with AI, semiconductor manufacturing, cloud computing and data-center infrastructure have attracted enormous investor enthusiasm.
The market rewarded companies for their potential rather than waiting for the full realization of their earnings.
That enthusiasm is now being tested.
READ: Akhlaq Siddiqi: | To orbit and back: The two firms reshaping power (November 21, 2026)
Investors are beginning to ask difficult questions. How much money will AI infrastructure actually generate? Can the enormous capital expenditures by major technology companies produce returns sufficient to justify current valuations? Will electricity, computing infrastructure and financing costs undermine the economics of the AI revolution?
These are legitimate questions. Artificial intelligence may fundamentally transform the global economy, but that does not mean every company associated with it is worth its current market valuation.
The distinction between technological transformation and investment returns is becoming increasingly important.
The estimated multitrillion-dollar destruction in global equity market capitalization should also be understood carefully. Market capitalization losses do not mean that an equivalent amount of cash has physically left the financial system. They reflect the reduction in the market value of outstanding shares.
Nevertheless, the scale of the decline demonstrates how quickly investor confidence can change.
Is India emerging as an alternative destination?
At the same time, India is experiencing a remarkable reversal in foreign investment flows.
Foreign portfolio investors reportedly directed approximately $12 billion into Indian equities during November (by November 20), a record monthly inflow according to contemporaneous reporting.
Granted, $12 billion is a relatively small amount compared with the enormous scale of investment in U.S. financial markets. But its significance lies less in the absolute figure than in what it may signal: a possible shift in investor sentiment toward India after months of foreign selling.
Whether this marks the beginning of a sustained reallocation of global capital or merely a temporary adjustment remains to be seen.
This is particularly significant because India had experienced substantial foreign selling over the preceding months.
The resurgence suggests that international investors are reconsidering India’s position in their global portfolios.
Several factors are contributing to this development.
First, India offers exposure to a different economic structure. Its stock market is supported by banking, financial services, telecommunications, infrastructure, automobiles, healthcare and domestic consumption. Unlike the American market, where a relatively small group of technology companies has driven a substantial portion of index performance, India’s investment opportunities are distributed across several sectors.
Second, lower crude oil prices can benefit India. As one of the world’s largest oil importers, India is particularly sensitive to energy prices. Lower oil prices can improve its current-account position, reduce inflationary pressure and support corporate profitability.
Third, India’s domestic financial system has become increasingly important. Domestic mutual funds, insurance companies and individual investors have provided substantial support to Indian equities, even during periods of foreign institutional selling.
The growth of systematic investment plans, or SIPs, has created a relatively consistent source of domestic investment demand.
This is an important structural difference. India’s market is no longer entirely dependent on foreign institutional capital.
Who is buying India?
The movement of international capital involves several categories of investors.
Global asset managers such as BlackRock, Vanguard, Fidelity and GQG Partners have exposure to Indian equities through various investment strategies. Sovereign wealth funds, including Singapore’s GIC and Temasek, as well as Norway’s sovereign wealth fund and Middle Eastern investment institutions, are also important participants in India’s investment landscape.
However, it is important not to assume that every one of these institutions was responsible for November’s buying. Aggregate foreign portfolio investment figures do not identify every individual fund’s transactions.
India’s domestic institutions may be even more important. The Life Insurance Corporation of India and major mutual fund companies such as SBI Mutual Fund, HDFC Mutual Fund, ICICI Prudential and Nippon India have become significant participants in the country’s equity markets.
Their presence creates a deeper domestic investment base.
The question is whether foreign investors are making a temporary allocation adjustment or beginning a longer-term reassessment of India’s position in emerging-market portfolios.
That distinction will determine whether the current rally has lasting significance.
Why isn’t America behaving like a safe haven?
Perhaps the most interesting aspect of the current market environment is the weakening of the traditional safe-haven relationship.
Historically, during periods of global uncertainty, investors sought protection in American Treasury securities and the U.S. dollar. The United States benefited from its deep financial markets, institutional credibility and the dollar’s dominant international position.
But the traditional relationship is becoming more complicated.
The enormous U.S. fiscal deficit, growing government debt, uncertainty about future inflation and questions surrounding Federal Reserve policy are creating additional concerns.
When investors worry about both equity valuations and the direction of interest rates, even traditional defensive investments can become less attractive.
There is also a concentration problem in the American equity market. A small number of enormous technology companies have acquired extraordinary influence over major stock indexes.
When investors begin questioning the valuations of those companies, the entire market can suffer.
This does not mean that the dollar is losing its reserve-currency position or that American financial markets have suddenly become irrelevant. The United States continues to possess unmatched financial depth and liquidity.
But the idea that American assets automatically provide protection during every period of uncertainty deserves closer examination.
Another possibility is that investors are not moving directly from American equities into Indian equities. Some may simply be raising cash, reducing leverage or moving into money-market instruments and short-term government securities.
Capital rotation should not be confused with a complete transfer of wealth between countries.
Is India becoming another global investment safe haven?
India’s recent performance is impressive, but it would be premature to call it a safe haven.
Indian equities carry their own risks. Valuations remain relatively expensive compared with many other emerging markets. The economy remains sensitive to international energy prices, currency movements and global financial conditions.
A sustained increase in oil prices could quickly undermine some of the factors supporting the Indian rally. A stronger dollar or a tightening of global liquidity could also reverse foreign investment flows.
Furthermore, a sudden surge in foreign buying does not necessarily indicate that investors intend to hold their positions for years.
India’s challenge is to convert its demographic advantages, domestic consumption and expanding industrial capacity into sustainable corporate earnings growth.
The opportunity is substantial, but expectations must remain realistic.
A changing global investment map?
The current divergence between Wall Street and Mumbai reflects a broader question about the future geography of global investment.
For many years, American technology companies were the primary beneficiaries of global investment enthusiasm. Artificial intelligence accelerated that trend, attracting capital on an extraordinary scale.
But investment cycles eventually confront the reality of earnings, cash flow and valuations.
The next phase may involve greater geographical diversification, with investors looking beyond the United States for growth opportunities.
India is well positioned to benefit from this reassessment. Its expanding economy, domestic savings, financial-sector development and infrastructure investment make it an important destination for international capital.
However, one month of record inflows cannot establish a permanent change in global investment preferences.
The evidence will come from the next several quarters: whether foreign institutional investors continue buying Indian equities, whether domestic institutions sustain their investment activity, and whether American technology companies can justify their enormous capital expenditures through actual earnings.
The most important development may not be that India is rising while America is falling. It may be that investors are beginning to question a financial assumption that has remained largely unquestioned for decades: that the United States is always the most attractive destination for global capital.
Wall Street is not finished, and India has not replaced it. But the global investment landscape may be entering a period in which capital becomes more selective, more geographically diversified and less willing to pay any price for the promise of technological growth.
The next chapter of global finance may be determined not simply by who develops the most transformative technology, but by where investors believe that technology, economic growth and actual financial returns will ultimately converge.