
By Palak Devpura
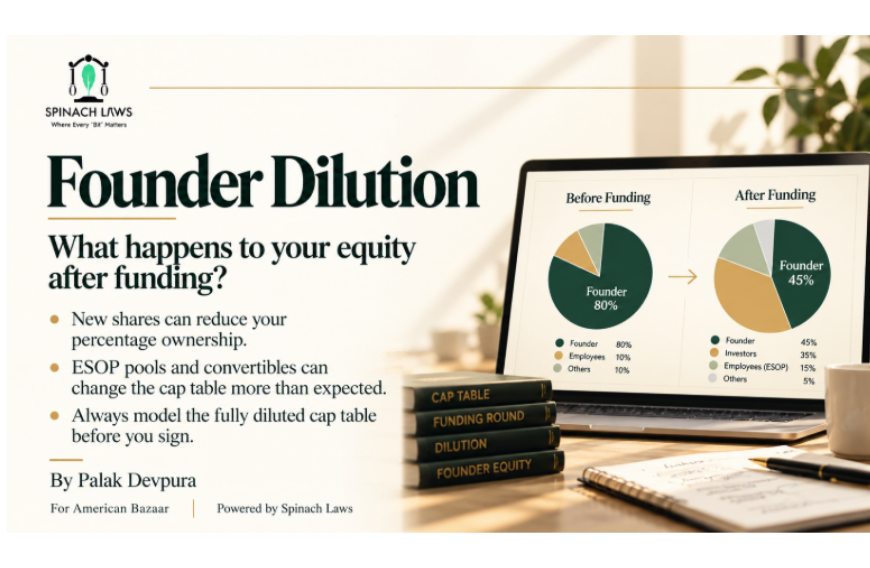
Imagine two founders start with 50 percent each. Then an angel invests. An ESOP pool is created. A seed round follows. By Series A, both founders still own shares, but neither is anywhere close to 50 percent.
Nothing necessarily went wrong. That is dilution.
Dilution happens when a company issues new shares or securities and the total number of shares increases. If you do not buy enough new shares to maintain your percentage, your percentage ownership falls. The important distinction is this: owning a smaller percentage of a much more valuable company can be perfectly rational. The problem begins when founders discover dilution only after the documents are signed.
Suppose a company is valued at ₹8 crore pre money and an investor puts in ₹2 crore. Ignoring other adjustments, the post money value is ₹10 crore and the new investor would economically represent 20 percent of that post money value. Existing holders are diluted into the remaining 80 percent. But real funding rounds are rarely that neat.
READ: What happens after a startup receives a term sheet? (October 13, 2026)
An ESOP pool can change the picture significantly. Investors often want sufficient employee equity available for future hiring. If the pool is increased before the investment, that dilution may fall primarily on existing founders and shareholders rather than the incoming investor. This is why the phrase 10 percent ESOP pool should immediately lead to a second question: 10 percent on what basis, and created when?
Convertible instruments can also alter the cap table. Notes, SAFE style instruments, CCPS or other convertibles may convert at discounts, valuation caps or agreed formulas. The headline valuation of the new round does not tell you the founder’s final ownership unless you model every outstanding instrument.
READ: The game within the game (May 9, 2026)
Then come anti dilution rights. These are designed to protect certain investors if the company later raises money at a lower valuation. Depending on the negotiated formula, an investor’s conversion economics may adjust, creating additional dilution for founders and other shareholders.
So what should a founder actually do? Maintain a fully diluted cap table, not just a list of issued shares. Model the cap table before signing the term sheet. Include the ESOP top up, outstanding convertibles and proposed new investment. Then run another scenario for the next round.
Dilution is not a failure. Unplanned dilution is.
The number founders should watch is not simply how much am I raising. It is this: what will I own, and what rights will I retain, when this round is finished?
(Palak Devpura is co-founder of Spinach Laws, a startup-focused legal services firm advising founders on incorporation, brand protection and cross-border transactions. This column is part of the ongoing Spinach Laws × The American Bazaar series on law for founders.)